Retirement planning your whole family can lean on.
I help Canadians 45 to 65 turn their savings into tax-efficient retirement income, protect the people they love, and pass on more. Clients say I take the time to explain everything clearly, and never rush them into a decision.
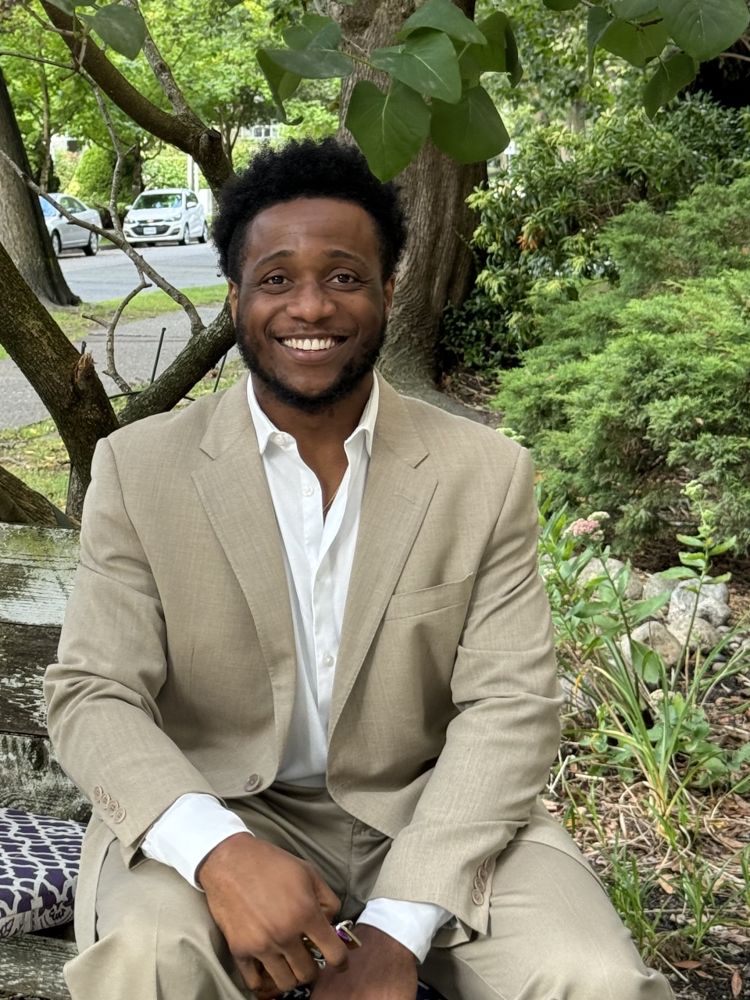
What's on your mind?
Pick the one that sounds like you. I'll take it from there.
"Am I on track to retire?"
See where you really stand, and how to draw income from your RRSP, TFSA and pensions with less tax.
Let's look →"Is my family protected?"
Life, critical illness and disability cover, so an illness or a death can't undo the plans you've made.
Let's look →"I run a business."
Build wealth inside your corporation, protect your key people, and plan your exit.
Let's look →The OHANA Signature Process
Ohana means family. Five steps, one plan your whole family stands on, and a full circle, because we come back to it every year.
- O
Open the conversation
Your goals and your family come first. We start with your story, not a product.
- H
Health check
Every account, pension and policy in one clear picture, so you see where you really stand.
- A
Add protection
Make sure an illness, an accident or a death can't undo everything you've built.
- N
Nurture growth
Put your money to work with less tax: TFSA, RRSP, segregated funds and insurance-based strategies.
- A
Arrange your legacy
Beneficiaries, estate costs and probate, so more reaches the people you love.
…and we check in every year, like family does ♥
I'll explain it like I would to my own family.
Most people I meet have been sold to before. I'd rather sit down, listen, and show you, clearly and patiently, what I'd do in your shoes. Sometimes that's an insurance policy. Sometimes it's simply changing the order you draw from your RRSP and TFSA. Either way, you'll understand why.
I'm an independent, licensed life insurance advisor working through HUB Financial, so I can compare options from many Canadian insurers, not just one.
Kind words from real families
★★★★★ 5.0 on Google. A few, in their own words:
★★★★★He never once rushed or pushed me into making a decision… I could see from the start he was an honest family man with strong values.
★★★★★Thoughtful, a great listener and gives very honest detailed advice. My daughter is now using his expertise as well… He truly makes you feel he has your back.
★★★★★He has helped me put important financial plans in place for myself and my family, including… my children's life insurance and investment plans, their RESPs for future education, and my TFSA.
★★★★★He takes the time to understand his clients, goes through the numbers carefully, and explains everything in a simple and clear way.
What happens on the free call
Twenty minutes, by phone or video. No cost, no obligation.
- 1
You tell me where you are
Your savings, your family, and what you want retirement to look like.
- 2
I show you what I'd look at
Clearly and simply: the gaps, the tax, and the options that could fit.
- 3
You decide
Nobody signs anything on a first call. If it isn't a fit, I'll tell you.
Honest answers to common questions
The things people usually wonder about before they book, but don't always ask.
Can life insurance help me retire with less tax in Canada?
For the right person, yes. A permanent policy such as universal life lets savings grow tax-sheltered inside the policy, and later you may be able to access that value through policy loans while the policy stays in force. It costs more than term insurance, works best over 10 years or more, and isn't right for everyone. That's exactly what the free call is for.
Isn't it smarter to "buy term and invest the difference"?
Sometimes it is, and I'll tell you when. Term is the cheapest way to cover a mortgage or young kids. Permanent coverage makes more sense when you want lifelong protection, have already used your TFSA and RRSP room, or want to leave a tax-efficient inheritance. Most families end up with a mix, and we'd compare both side by side.
Isn't permanent life insurance expensive?
It costs more than term, because it lasts your whole life and builds value. That's why we start with what you actually need and what fits your budget. If term alone does the job, that's what I'll recommend.
I already have life insurance through work. Isn't that enough?
It's a great start, but group coverage is often only one or two times your salary, and it usually ends when you leave the job or retire, right when your health makes new coverage harder to get. We'll check what you have and whether there's a gap.
Is it too late to start planning at 55?
No. At 55 you usually still have 10 or more years of earning, and choices like the order you draw from your RRSP, TFSA and pensions, and when you take CPP and OAS, can make a real difference to your retirement income.
What if my health isn't perfect?
You may still qualify. Different insurers look at health very differently, and some offer simplified or no-medical options. Because I work with many Canadian insurers, I can shop your situation around instead of relying on one company's answer.
What happens to my RRSP when I die?
Unless it rolls over to a spouse or an eligible dependant, the full value of an RRSP or RRIF is generally added to your income on your final tax return, which can mean a large tax bill for your estate. Planning ahead can soften that, and it's one of the first things we look at.
What if I need my money before retirement?
Your plan should never lock away your emergency money. We keep easy-access savings separate, and if you use a permanent policy, its cash value can usually be accessed through withdrawals or policy loans, though that can reduce the value and the death benefit. I'll walk you through the trade-offs before you decide anything.
Is my money safe if an insurance company fails?
Canadian life insurers are regulated, and Assuris, a not-for-profit organization, protects policyholders of its member companies if one fails. I only work with well-established Canadian insurers.
I already have an advisor or a bank. Why talk to you?
A second opinion costs nothing. Banks can usually only offer their own products, while I'm independent through HUB Financial and can compare options from many insurers. Plenty of people keep their current advisor and simply fill a gap with me.
Will I be rushed into buying something?
No. Clients often say I never rushed or pushed them into a decision. The first call is about understanding your situation, and nobody signs anything on it. If what you have is already working, I'll tell you.
How are you paid?
The call and the plan cost you nothing. If you choose to put an insurance policy or investment in place, I'm paid a commission by the insurance company.
Do you only work with people in Surrey?
No. I'm licensed in British Columbia, Ontario, Alberta, Manitoba and Nova Scotia, and meet by video or phone.
Still wondering about something? Ask me on a free call.
Pull up a chair.
A free 20-minute call. You talk, I listen, and you leave with a clearer picture, whether or not we work together.
Prefer to call? 604-800-7647